
Pradhan Mantri Mudra Yojana (PMMY)
Pradhan Mantri Mudra Yojana provides collateral-free institutional credit to eligible micro enterprises in non-farm income-generating activities. Loans are available under Shishu, Kishore, Tarun and Tarun Plus categories, with the maximum loan limit reaching ₹20 lakh under Tarun Plus for eligible entrepreneurs who have successfully repaid a previous Tarun loan.
1. Scheme Objectives & Overview
PMMY can support both term loan and working capital requirements for eligible activities. The scheme covers manufacturing, trading and service-sector activities, including activities allied to agriculture such as poultry, dairy and beekeeping.
Loan categories:
• Shishu: Loans up to ₹50,000.
• Kishore: Loans above ₹50,000 and up to ₹5 lakh.
• Tarun: Loans above ₹5 lakh and up to ₹10 lakh.
• Tarun Plus: Loans above ₹10 lakh and up to ₹20 lakh for entrepreneurs who have successfully repaid a previous Tarun-category loan. Tarun Plus became applicable with effect from 24 October 2024.
PMMY does not provide a fixed Government subsidy to the borrower. It is primarily a credit scheme. The main benefit is access to collateral-free institutional credit, while the interest rate is decided by the lending institution in accordance with applicable RBI guidelines and its own lending policy.
Collateral and guarantee:
• PMMY loans are available on a collateral-free basis.
• Credit guarantee support for eligible PMMY loans is provided through the Credit Guarantee Fund for Micro Units (CGFMU).
• The guarantee structure does not mean that every loan application is automatically approved. The lending institution still assesses the borrower, business viability, repayment capacity and applicable credit norms.
Interest rate and charges:
• There is no single uniform PMMY interest rate fixed for every borrower.
• The applicable interest rate is determined by the Member Lending Institution (MLI) based on its lending policy and applicable RBI guidelines.
• Banks may levy upfront or processing charges according to their internal guidelines.
• For Shishu loans up to ₹50,000, processing charges are waived by most banks as stated in the scheme information.
Eligible borrowers:
• Individuals.
• Proprietary concerns.
• Partnership firms.
• Private Limited Companies.
• Public Companies.
• Other eligible legal forms, subject to the lending institution and scheme requirements.
The borrower should not be a defaulter to any bank or financial institution and should have a satisfactory credit track record. Individual borrowers may also need the relevant skills, experience or knowledge required for the proposed activity. Educational qualification, wherever relevant, is assessed according to the nature of the business.
Eligible activities:
• Manufacturing activities.
• Trading activities.
• Service-sector activities.
• Non-farm income-generating micro enterprises.
• Activities allied to agriculture such as poultry, dairy and beekeeping.
PMMY can support a wide range of small businesses such as shops, repair units, food-service businesses, artisans, food processors, transport operators, machine operators, vendors and other eligible micro enterprises.
Application process:
• Visit the PM MUDRA official website and access the applicable online loan application route such as Udyamimitra or the relevant lending platform.
• Select Mudra Loan Apply Now.
• Choose the applicable applicant type such as new entrepreneur, existing entrepreneur or self-employed professional.
• Enter applicant details including name, email and mobile number and complete OTP verification.
• Fill in personal and professional details.
• Select a hand-holding agency if assistance is required for project preparation, or proceed to the loan application centre.
• Select the applicable loan category: Shishu, Kishore, Tarun or Tarun Plus.
• Enter business information including business name, activity and industry type.
• Provide owner details, existing banking or credit facilities, proposed credit facilities, estimates and preferred lender.
• Upload the required documents.
• Submit the application and retain the generated Application Number for future reference.
PMMY is also available through JanSamarth for eligible applicants and participating lending institutions.
Documents required:
• Identity proof such as Aadhaar Card, PAN Card, Voter ID, Driving Licence, Passport or another accepted Government-issued photo ID.
• Address proof of the applicant or relevant proprietor, partners or directors, as applicable.
• Recent passport-size photograph.
• Applicant signature.
• Business identity and address proof, such as relevant licences, registrations or other ownership and address documents.
• Machinery or equipment quotation where applicable.
• Details of the proposed machinery, supplier and cost where applicable.
• For higher-value or existing-business cases, bank statements, balance sheets, tax returns, projected financial statements and project reports may be required.
• Partnership deed, Memorandum and Articles of Association or other constitutional documents, depending on the legal structure.
Documentation can vary according to the lender, business structure, loan amount and whether the application is for a new or existing business.
Important points before applying:
• There is no Government-appointed agent or middleman for obtaining a PMMY loan. Applicants should avoid people claiming to be MUDRA or PMMY agents.
• Approval is not automatic merely because the applicant falls within an eligible category.
• The lending institution assesses business viability, repayment capacity, credit history, documentation and other applicable requirements.
• A previous Tarun loan must have been successfully repaid to qualify for Tarun Plus.
• PMMY should not be confused with a subsidy scheme. The principal benefit is collateral-free credit, not a direct subsidy payment.
As per the latest Department of Financial Services information, PMMY now provides collateral-free loans up to ₹20 lakh through the four categories, including Tarun Plus. The current official Ministry information also confirms that term loan as well as working capital requirements can be met under PMMY.
2. Eligibility Criteria & Beneficiary Qualifications
Eligible borrower types
Eligibility is subject to the applicable lender and scheme requirements.
Eligible business activity
The proposed activity must qualify as an eligible income-generating micro enterprise activity under PMMY.
Default status
A satisfactory credit track record is expected.
Skills / experience / knowledge
Requirement depends on the nature of the proposed activity.
Previous Tarun loan repayment
Tarun Plus applies to entrepreneurs who have successfully repaid previous Tarun-category loans.
Income-generating enterprise
PMMY is intended for income-generating micro enterprises.
3. Mandatory Documents Required
Identity Proof
Accepted identity proof such as Aadhaar Card, PAN Card, Voter ID, Driving Licence, Passport or another Government-issued photo ID.
Address Proof
Recent accepted address proof of the applicant or relevant proprietor, partners or directors as applicable.
Passport-size Photograph
Recent passport-size photograph of the applicant.
Applicant Signature
Applicant signature as required by the lender and application process.
Business Identity and Address Proof
Relevant licences, registration certificates or other documents establishing the ownership, identity and address of the business enterprise.
Machinery / Equipment Quotation
Quotation and supplier details for machinery or other items proposed to be purchased, where applicable.
Financial Statements / Bank Statements
Existing-business applicants and higher-value cases may be asked for bank statements, balance sheets, tax returns and projected financial statements.
Project Report / Constitutional Documents
Project report and applicable Partnership Deed, Memorandum and Articles of Association or other legal documents depending on the entity and loan case.
4. Standard Application & Approval Process
DPR Formulation & Supplier Quotations
Prepare a Detailed Project Report itemizing machinery costs, power load sanction, and working capital needs from GST-registered suppliers.
Online Portal Registration & Upload
Register on the designated official nodal portal (e.g. JanSamarth.in or KVIC online) with Aadhaar, PAN, Udyam, and select your preferred bank branch.
DTFC Review & Bank Credit Appraisal
District Task Force Committee (DTFC) verifies eligibility and forwards the proposal to the bank branch for credit assessment and sanction letter issuance.
Disbursement & 3-Year TDR Subsidy Lock-In
Upon borrower margin deposit (5% - 15%), the bank disburses credit. The subsidy is parked in an interest-free 3-year TDR and credited against principal upon audit.
Eligible Business Blueprints for Pradhan Mantri Mudra Yojana (PMMY)
Verified enterprise blueprints and project models eligible for capital subsidies and credit support under this scheme.
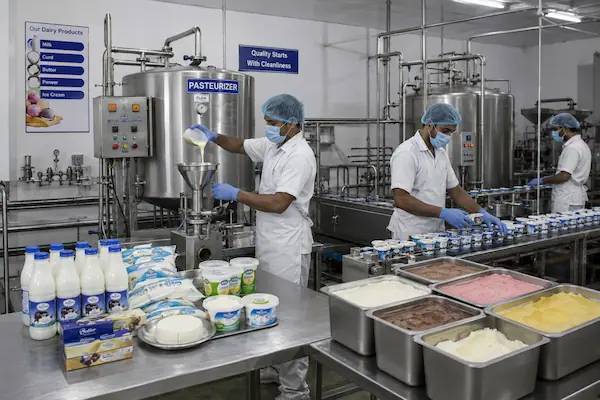
Ice Cream and Dairy Products Manufacturing Business
Build a dairy processing business around ice cream, frozen dairy desserts and selected dairy products, starting with a small controlled production setup and scaling into a commercial cold-chain operation.
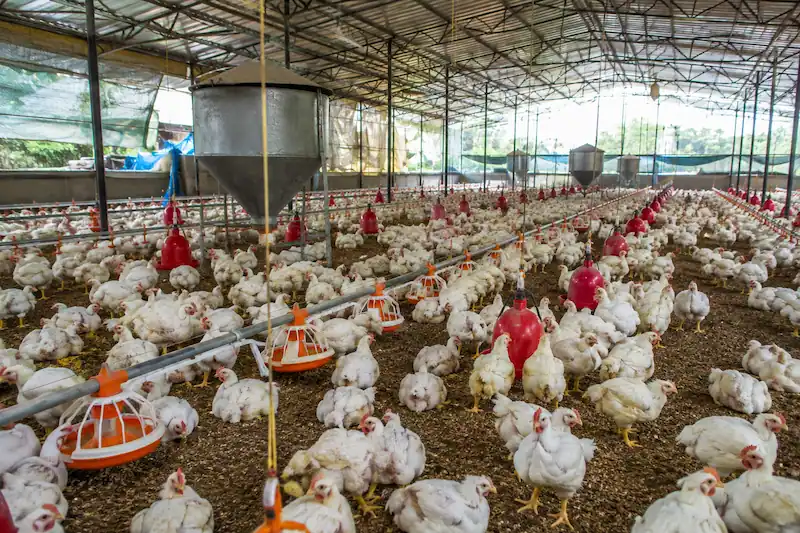
Poultry Farming Business
Start a poultry farm at the scale that matches your land and capital, from a small broiler unit using an existing shed to a commercial broiler or layer farm with dedicated housing, equipment, biosecurity and working capital.
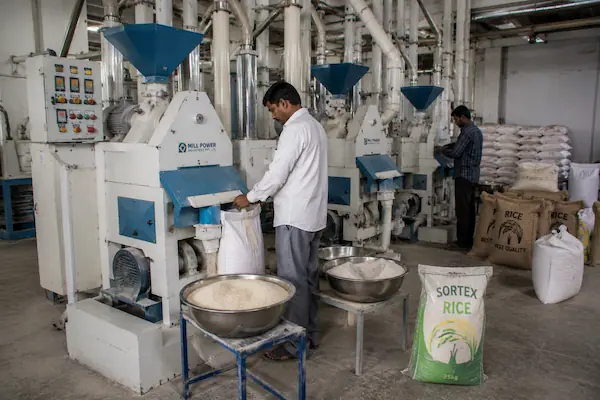
Mini Rice Mill Business
Start a mini rice mill for custom paddy milling or build a small commercial rice-processing operation with hulling, polishing, grading and packing as production volume grows.
Frequently Asked Questions
Everything you need to know about eligibility, subsidy disbursement, and application timelines for Pradhan Mantri Mudra Yojana (PMMY).
Pradhan Mantri Mudra Yojana (PMMY) is a Government scheme for collateral-free institutional credit to eligible micro enterprises. Loans are available under Shishu up to ₹50,000, Kishore up to ₹5 lakh, Tarun up to ₹10 lakh and Tarun Plus above ₹10 lakh up to ₹20 lakh for eligible borrowers who have successfully repaid a previous Tarun loan.
No. PMMY is primarily a credit scheme and does not provide a fixed direct Government subsidy to the borrower. Its main benefit is access to collateral-free institutional credit through eligible lending institutions.
PMMY loans are designed to be collateral-free. However, the lender still evaluates the borrower, business viability, repayment capacity, credit history and applicable lending norms before sanctioning the loan.
There is no single uniform PMMY interest rate for every borrower. The applicable interest rate is determined by the Member Lending Institution according to its lending policy and applicable RBI guidelines.
Tarun Plus is intended for entrepreneurs who have availed and successfully repaid a previous Tarun-category loan. Therefore, simply requesting ₹20 lakh does not by itself make a new borrower eligible for Tarun Plus.
Yes. New entrepreneurs can apply under the applicable PMMY category, subject to the lender's appraisal and the scheme requirements. The proposed activity must be eligible and income-generating, and the borrower must meet the lender's credit and documentation requirements.
Possible reasons include poor credit history or default, weak business viability, inadequate repayment capacity, incomplete documents, unsuitable or ineligible business activity, insufficient lender assessment, or failure to satisfy the specific conditions of the selected loan category such as Tarun Plus eligibility.
Ready to Apply for Pradhan Mantri Mudra Yojana (PMMY)?
Get official eligibility guidelines, mandatory document checklists, and direct online nodal portal application access — 100% free.