
प्रधानमंत्री मुद्रा योजना (PMMY)
प्रधानमंत्री मुद्रा योजना गैर-कृषि आय-सृजन गतिविधियों वाले पात्र सूक्ष्म उद्यमों को बिना collateral institutional credit उपलब्ध कराती है। Shishu, Kishore, Tarun और Tarun Plus categories में loan मिलता है। पात्र borrowers के लिए Tarun Plus के तहत अधिकतम loan limit ₹20 लाख तक है, बशर्ते उन्होंने पहले Tarun category का loan सफलतापूर्वक repay किया हो।
1. योजना के उद्देश्य एवं मुख्य विवरण
PMMY के तहत eligible businesses के लिए term loan और working capital दोनों जरूरतें पूरी की जा सकती हैं। इसमें manufacturing, trading और service activities के साथ poultry, dairy और beekeeping जैसी agriculture-allied activities भी शामिल हैं।
Loan categories:
• Shishu: ₹50,000 तक का loan।
• Kishore: ₹50,000 से अधिक और ₹5 लाख तक का loan।
• Tarun: ₹5 लाख से अधिक और ₹10 लाख तक का loan।
• Tarun Plus: ₹10 लाख से अधिक और ₹20 लाख तक का loan उन entrepreneurs के लिए जिन्होंने पहले Tarun category का loan सफलतापूर्वक repay किया है। Tarun Plus 24 अक्टूबर 2024 से लागू हुआ।
PMMY में borrower को कोई fixed Government subsidy नहीं दी जाती। यह मुख्य रूप से एक credit scheme है। इसका मुख्य लाभ collateral-free institutional credit तक पहुंच है। Interest rate lending institution अपनी lending policy और applicable RBI guidelines के अनुसार तय करता है।
Collateral और guarantee:
• PMMY loans collateral-free basis पर उपलब्ध होते हैं।
• Eligible PMMY loans के लिए credit guarantee support Credit Guarantee Fund for Micro Units (CGFMU) के माध्यम से उपलब्ध है।
• Credit guarantee का मतलब automatic loan approval नहीं है। Bank या lending institution borrower की repayment capacity, business viability, credit history और applicable norms को assess करता है।
Interest rate और charges:
• सभी borrowers के लिए PMMY की एक fixed uniform interest rate नहीं है।
• Applicable interest rate Member Lending Institution (MLI) अपनी lending policy और RBI guidelines के अनुसार तय करती है।
• Banks अपनी internal guidelines के अनुसार upfront या processing charges ले सकते हैं।
• ₹50,000 तक के Shishu loan पर अधिकांश banks processing charges waive करते हैं, जैसा scheme information में बताया गया है।
Eligible borrowers:
• Individuals.
• Proprietary concerns.
• Partnership firms.
• Private Limited Companies.
• Public Companies.
• अन्य eligible legal forms, subject to lender और scheme requirements.
Borrower किसी bank या financial institution का defaulter नहीं होना चाहिए और उसका satisfactory credit track record होना चाहिए। Individual borrower के पास proposed business करने के लिए आवश्यक skills, experience या knowledge भी मांगी जा सकती है। जहां जरूरी हो, educational qualification business की nature के अनुसार assess की जाती है।
Eligible activities:
• Manufacturing activities.
• Trading activities.
• Service-sector activities.
• Non-farm income-generating micro enterprises.
• Poultry, dairy और beekeeping जैसी agriculture-allied activities.
PMMY के तहत shops, repair units, food-service businesses, artisans, food processors, transport operators, machine operators, vendors और अन्य eligible micro enterprises को credit support मिल सकता है।
Application process:
• PM MUDRA की official website पर जाकर applicable online loan application route जैसे Udyamimitra या relevant lending platform access करें।
• Mudra Loan Apply Now option चुनें।
• New entrepreneur, existing entrepreneur या self-employed professional में applicable option चुनें।
• Applicant का name, email और mobile number भरकर OTP verification पूरा करें।
• Personal और professional details भरें।
• Project proposal बनाने में सहायता चाहिए तो hand-holding agency select करें या loan application centre से आगे बढ़ें।
• Applicable loan category चुनें: Shishu, Kishore, Tarun या Tarun Plus।
• Business name, activity और industry type सहित business information भरें।
• Owner details, existing banking या credit facilities, proposed credit facilities, estimates और preferred lender की details दें।
• Required documents upload करें।
• Application submit करें और generated Application Number future reference के लिए सुरक्षित रखें।
Eligible applicants के लिए PMMY JanSamarth platform के माध्यम से भी उपलब्ध है।
Documents required:
• Identity proof जैसे Aadhaar Card, PAN Card, Voter ID, Driving Licence, Passport या अन्य accepted Government-issued photo ID।
• Applicant या applicable proprietor, partners या directors का address proof।
• Recent passport-size photograph।
• Applicant signature।
• Business identity और address proof, जैसे relevant licences, registrations या ownership/address documents।
• जहां लागू हो machinery या equipment quotation।
• जहां applicable हो proposed machinery, supplier और cost की details।
• Higher-value या existing-business cases में bank statements, balance sheets, tax returns, projected financial statements और project report मांगे जा सकते हैं।
• Business structure के अनुसार partnership deed, Memorandum and Articles of Association या अन्य constitutional documents।
Documents lender, business structure, loan amount और new या existing business के अनुसार अलग हो सकते हैं।
Apply करने से पहले जरूरी बातें:
• PMMY loan लेने के लिए कोई Government-appointed agent या middleman नहीं है। MUDRA या PMMY का agent बताने वाले लोगों से सावधान रहें।
• केवल eligible category में होने से loan approval automatic नहीं होता।
• Lending institution business viability, repayment capacity, credit history, documents और applicable requirements assess करती है।
• Tarun Plus के लिए previous Tarun loan का successful repayment जरूरी है।
• PMMY को subsidy scheme न समझें। इसका मुख्य benefit collateral-free credit है, direct subsidy payment नहीं।
Department of Financial Services की latest information के अनुसार PMMY की maximum collateral-free loan limit अब ₹20 लाख तक है और इसके लिए Shishu, Kishore, Tarun और Tarun Plus की four-category structure लागू है। Official Ministry information यह भी confirm करती है कि PMMY में term loan और working capital दोनों जरूरतें पूरी की जा सकती हैं।
2. पात्रता मानदंड एवं लाभार्थी योग्यताएं
पात्र borrower प्रकार
Eligibility is subject to the applicable lender and scheme requirements.
पात्र business activity
The proposed activity must qualify as an eligible income-generating micro enterprise activity under PMMY.
Default status
A satisfactory credit track record is expected.
Skill / experience / knowledge
Requirement depends on the nature of the proposed activity.
पिछले Tarun loan की repayment
Tarun Plus applies to entrepreneurs who have successfully repaid previous Tarun-category loans.
आय-सृजन करने वाला enterprise
PMMY is intended for income-generating micro enterprises.
3. आवेदन हेतु आवश्यक दस्तावेज
Identity Proof
Aadhaar Card, PAN Card, Voter ID, Driving Licence, Passport या अन्य Government-issued photo ID जैसे स्वीकार्य पहचान प्रमाण।
Address Proof
Applicant या लागू proprietor, partners या directors का recent स्वीकार्य address proof।
Passport-size Photograph
Applicant की recent passport-size photograph।
Applicant Signature
Lender और application process के अनुसार applicant का signature।
Business Identity and Address Proof
Business enterprise की ownership, identity और address साबित करने वाले relevant licences, registration certificates या अन्य documents।
Machinery / Equipment Quotation
जहां लागू हो, खरीदी जाने वाली machinery या अन्य items की quotation और supplier details।
Financial Statements / Bank Statements
Existing business और higher-value cases में bank statements, balance sheets, tax returns और projected financial statements मांगे जा सकते हैं।
Project Report / Constitutional Documents
Entity और loan case के अनुसार project report, Partnership Deed, Memorandum and Articles of Association या अन्य legal documents।
4. चरणबद्ध आवेदन एवं स्वीकृति प्रक्रिया
प्रोजेक्ट रिपोर्ट (DPR) व मशीनरी कोटेशन
जीएसटी पंजीकृत सप्लायर्स से मशीनरी कोटेशन और बिजली लोड के साथ विस्तृत प्रोजेक्ट रिपोर्ट (DPR) तैयार करें।
सरकारी पोर्टल पर ऑनलाइन आवेदन
जनसमर्थ या अधिकृत नोडल पोर्टल पर आधार, पैन, उद्यम रजिस्ट्रेशन के साथ आवेदन करें और पसंदीदा बैंक शाखा चुनें।
टास्क फोर्स समीक्षा एवं बैंक अप्रूवल
जिला टास्क फोर्स कमेटी द्वारा पात्रता सत्यापन के बाद प्रस्ताव बैंक को लोन स्वीकृति हेतु भेजा जाता है।
लोन वितरण एवं सब्सिडी समायोजन
उद्यमी का अंशदान (5% - 15%) जमा होने पर लोन जारी होता है और 3 वर्ष बाद सब्सिडी मूलधन में समायोजित कर दी जाती है।
प्रधानमंत्री मुद्रा योजना (PMMY) के तहत पात्र बिजनेस मॉडल्स
इस योजना के तहत वित्तीय सहायता और लोन के लिए पात्र सत्यापित बिजनेस मॉडल्स।
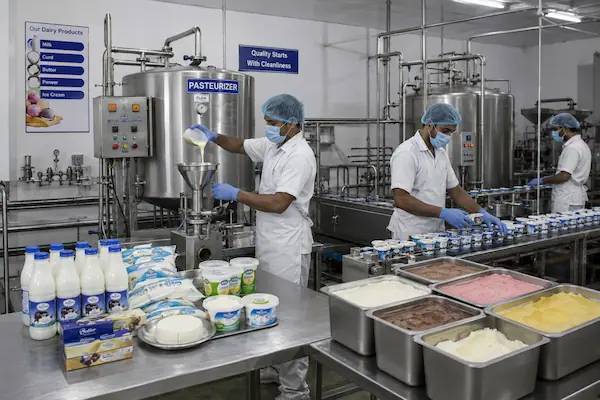
आइसक्रीम और डेयरी प्रोडक्ट्स मैन्युफैक्चरिंग बिजनेस
आइसक्रीम, फ्रोजन डेयरी डेजर्ट और चुनिंदा डेयरी उत्पादों पर आधारित बिजनेस छोटे नियंत्रित उत्पादन सेटअप से शुरू करके कमर्शियल कोल्ड-चेन ऑपरेशन तक बढ़ाया जा सकता है।
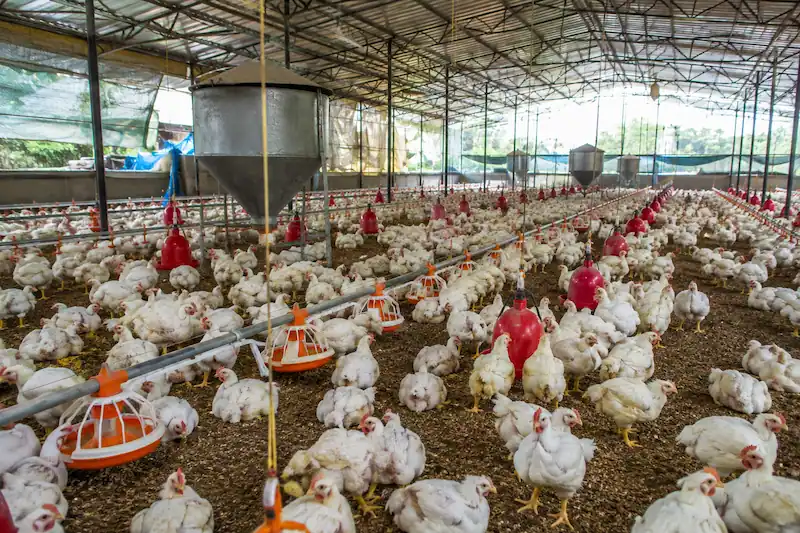
पोल्ट्री फार्मिंग बिजनेस
अपनी जमीन और पूंजी के अनुसार पोल्ट्री फार्म शुरू करें, मौजूदा शेड वाले छोटे ब्रॉयलर यूनिट से लेकर डेडिकेटेड शेड, उपकरण, बायोसिक्योरिटी और वर्किंग कैपिटल वाली कमर्शियल ब्रॉयलर या लेयर फार्म तक।
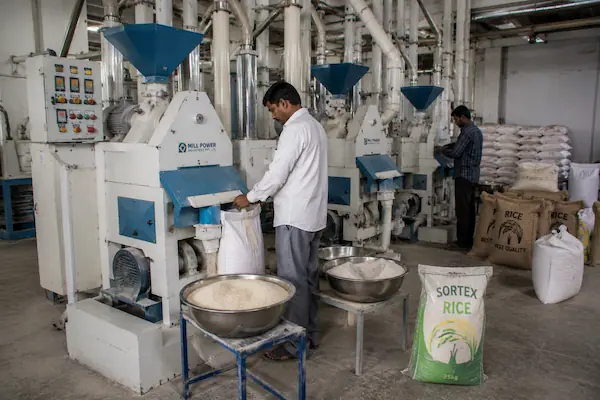
मिनी राइस मिल बिजनेस
कस्टम धान पिसाई से मिनी राइस मिल शुरू करें या उत्पादन बढ़ने पर हुलिंग, पॉलिशिंग, ग्रेडिंग और पैकिंग वाली छोटी कमर्शियल राइस प्रोसेसिंग यूनिट बनाएं।
अक्सर पूछे जाने वाले सवाल
प्रधानमंत्री मुद्रा योजना (PMMY) की पात्रता, सब्सिडी वितरण और आवेदन समयसीमा से जुड़े मुख्य सवाल।
Pradhan Mantri Mudra Yojana (PMMY) is a Government scheme for collateral-free institutional credit to eligible micro enterprises. Loans are available under Shishu up to ₹50,000, Kishore up to ₹5 lakh, Tarun up to ₹10 lakh and Tarun Plus above ₹10 lakh up to ₹20 lakh for eligible borrowers who have successfully repaid a previous Tarun loan.
No. PMMY is primarily a credit scheme and does not provide a fixed direct Government subsidy to the borrower. Its main benefit is access to collateral-free institutional credit through eligible lending institutions.
PMMY loans are designed to be collateral-free. However, the lender still evaluates the borrower, business viability, repayment capacity, credit history and applicable lending norms before sanctioning the loan.
There is no single uniform PMMY interest rate for every borrower. The applicable interest rate is determined by the Member Lending Institution according to its lending policy and applicable RBI guidelines.
Tarun Plus is intended for entrepreneurs who have availed and successfully repaid a previous Tarun-category loan. Therefore, simply requesting ₹20 lakh does not by itself make a new borrower eligible for Tarun Plus.
Yes. New entrepreneurs can apply under the applicable PMMY category, subject to the lender's appraisal and the scheme requirements. The proposed activity must be eligible and income-generating, and the borrower must meet the lender's credit and documentation requirements.
Possible reasons include poor credit history or default, weak business viability, inadequate repayment capacity, incomplete documents, unsuitable or ineligible business activity, insufficient lender assessment, or failure to satisfy the specific conditions of the selected loan category such as Tarun Plus eligibility.
क्या आप प्रधानमंत्री मुद्रा योजना (PMMY) के लिए आवेदन करने हेतु तैयार हैं?
आधिकारिक पात्रता नियम, आवश्यक दस्तावेजों की सूची और सीधे नोडल पोर्टल पर निःशुल्क ऑनलाइन आवेदन करें।